When it comes to managing money, most people assume that financial success depends almost entirely on knowledge, mathematical formulas, and complex market analysis.
However, real-world financial results are rarely dictated by how smart you are. Instead, they are driven by how you behave.
Understanding the psychology of money means recognizing that human emotions—such as fear, greed, status-seeking, and impatience—exert a far greater influence on our financial choices than spreadsheets ever will.
In this comprehensive guide, we explore the core psychological principles, cognitive biases, and behavioral mindsets that determine long-term wealth accumulation and financial peace of mind.
Part 1: Deconstructing How We Think About Money
Our relationship with money is formed long before we receive our first paycheck. Personal experiences, upbringing, and cultural influences shape our internal belief systems regarding wealth and risk.
+-------------------------------------------------------+
|             THE BEHAVIORAL WEALTH MATRIX              |
|                                                       |
|  Financial Knowledge  +  Emotional Discipline         |
|             \                   /                     |
|              \                 /                      |
|            SUSTAINABLE LONG-TERM WEALTH               |
+-------------------------------------------------------+
1. Recognize Your Personal “Money Scripts”
Psychologists refer to unconscious beliefs about money as “money scripts.” These internalized attitudes guide daily spending, saving, and investing behaviors without us actively realizing it.
Most money mindsets fall into four primary categories:
- Money Avoidance: The belief that money is corrupting, unethical, or a source of anxiety. Individuals with this script often sabotage their own financial growth.
- Money Worship: The assumption that earning more money or buying more possessions will automatically solve all life problems and grant happiness.
- Money Status: Equating net worth directly with self-worth, leading to overspending on status symbols to project success.
- Money Vigilance: Viewing money as a tool for safety, requiring careful saving, low debt, and ongoing risk management.
Identifying which belief system dominates your thinking allows you to correct unhealthy financial behaviors at their root.
2. Overcome the “Keep Up with the Joneses” Trap
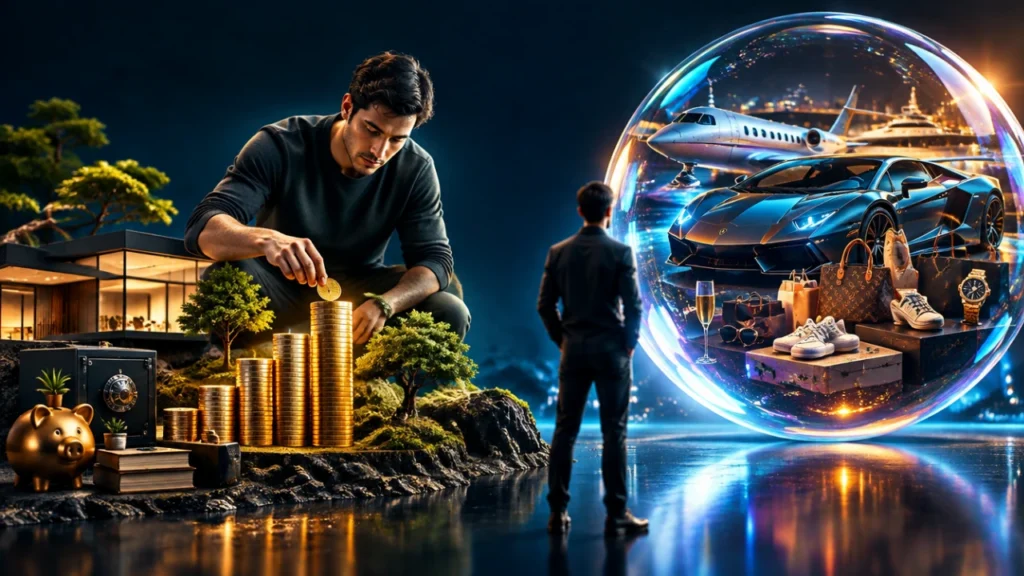
Social comparison is one of the most destructive psychological barriers to wealth accumulation. In a hyper-connected world dominated by social media highlight reels, it is easy to mistake visible spending for actual wealth.
True wealth is what you do not see:
- It is the unspent income converted into investments.
- It is the emergency buffer keeping you out of debt.
- It is the freedom to control your time and career.
When you buy luxury goods or upgrade your lifestyle solely to impress others, you trade long-term financial security for temporary external validation.
3. Shift from Rational Logic to Behavioral Psychology
Standard economic theory assumes that humans act as rational decision-makers who always maximize long-term utility. In reality, human beings are emotional creatures driven by immediate comfort and instinct.
Rational vs. Behavioral Money Management
| Dimension | Theoretical Rational Approach | Practical Behavioral Approach |
| Primary Goal | Maximize mathematical investment returns | Minimize psychological stress and anxiety |
| Debt Strategy | Focus strictly on interest rates (Avalanche) | Focus on emotional momentum (Snowball) |
| Risk Tolerance | Determined by age and quantitative metrics | Determined by your ability to sleep at night |
| Budgeting | Manual tracking down to every single cent | Automated system removing daily willpower |
Part 2: Cognitive Biases that Threaten Your Wealth
The human brain relies on cognitive shortcuts (heuristics) to make decisions quickly. While helpful in everyday survival, these mental shortcuts frequently lead to catastrophic financial mistakes.
Summary Table: Common Behavioral Biases in Finance
| Cognitive Bias | Behavioral Symptom | Financial Impact | Countermeasure |
| Loss Aversion | Feeling the pain of loss twice as hard as gain | Panic selling during market drops | Long-term asset allocation plan |
| Present Bias | Preferring instant rewards over future security | Chronic undersaving and impulse buying | Automated savings on payday |
| Confirmation Bias | Seeking only news that agrees with your views | Overconfidence in bad investments | Seeking counter-arguments actively |
| Anchor Effect | Fixing on a past price point (e.g., peak stock price) | Refusing to sell losing assets | Objective periodic reviews |
4. Master Loss Aversion and Panic Reactions
Behavioral economists Daniel Kahneman and Amos Tversky demonstrated that the psychological pain of losing $1,000 is twice as intense as the joy of gaining $1,000. This asymmetry is known as Loss Aversion.
In financial markets, loss aversion triggers panic selling:
- The market experiences a natural downturn.
- Investors feel severe anxiety as portfolio values drop on paper.
- To stop the emotional pain, they sell their assets at the bottom, locking in real losses.
- They miss the subsequent market recovery due to fear.
To combat loss aversion, create a written investment policy statement during calm market conditions that dictates how you will react during market corrections.
5. Defeat Present Bias Through System Automation
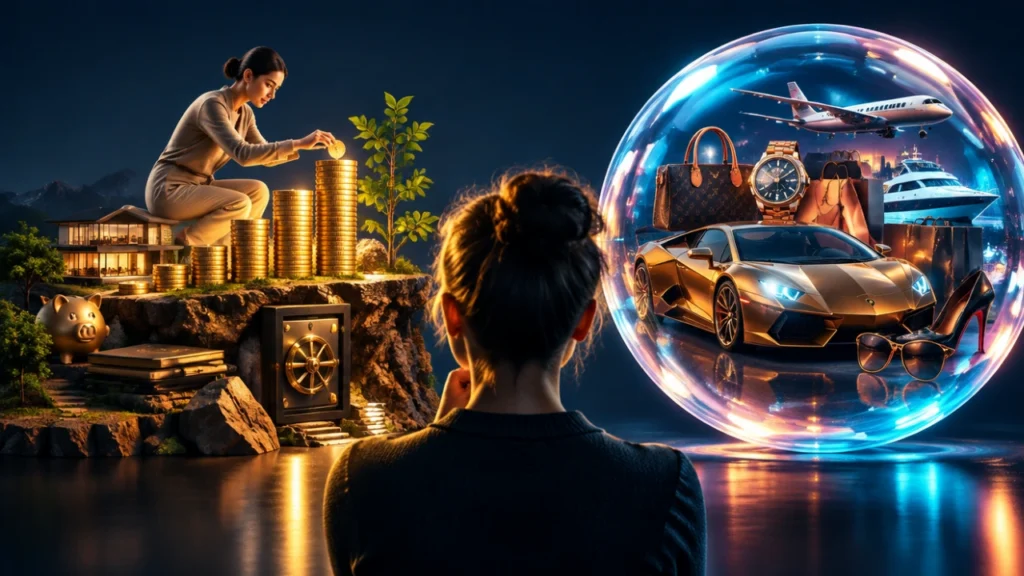
Present Bias is the human tendency to overvalue immediate rewards while heavily discounting future outcomes. It is the reason why spending $200 on a vacation today feels far more satisfying than saving $200 for a retirement decades away.
Because willpower fluctuates throughout the day, relying on discipline to save money consistently is a flawed strategy.
The psychological solution is pre-commitment:
- Automate retirement contributions directly from your paycheck.
- Set up recurring transfers to investment accounts on the day you are paid.
- Force your future self to save by removing manual decision-making entirely.
6. Avoid the Sunk Cost Fallacy in Financial Choices
The Sunk Cost Fallacy occurs when you continue pouring money, time, or emotional energy into a losing investment simply because you have already invested heavily in it.
Examples include:
- Holding onto a failing stock because “I can’t sell until I get back to break-even.”
- Continuing to pay repair bills on a unreliable car because you just spent money fixing it last month.
To make clean financial decisions, evaluate your assets based on their future value and expected return, not on what you paid in the past.
Part 3: Emotional Mastery and Decision-Making Frameworks
Achieving long-term wealth requires developing emotional discipline and robust decision-making habits that survive market volatility and social pressure.
7. Define Your “Enough”: The Power of Contentment
One of the hardest financial skills to master is stopping the goalposts from moving. As your income increases and your net worth grows, your expectations naturally expand alongside them.
If your desire for more always keeps pace with your earnings:
- You will never feel financially secure, regardless of your balance sheet.
- You will take on unnecessary financial risk trying to pursue higher returns.
- You remain trapped in a cycle of perpetual consumption.
Establishing a clear definition of “Enough” allows you to lock in financial independence and direct excess capital toward meaningful goals rather than endless consumption.
8. Develop High “Margin of Safety” in Financial Planning
In engineering, structures are designed to hold far more weight than expected to prevent failure. In personal finance, this concept is called the Margin of Safety.
A strong margin of safety protects you against errors in judgment, bad luck, or unexpected economic downturns:
- Overestimate future expenses by 10% when projecting annual budgets.
- Underestimate expected investment returns when calculating retirement timelines.
- Maintain cash reserves beyond basic emergency needs to capture market opportunities.
When your plan depends on everything going perfectly, your plan is inherently fragile.
9. Understand the True Price of Financial Independence
Everything in life has a price, but the price of financial success is rarely listed on a price tag. The fee for long-term investment returns is volatility, uncertainty, doubt, and patience.
[ Financial Market Returns ] <--- Paid for with ---> [ Volatility & Emotional Patience ]
When the stock market drops 20% in a year, view that decline as an admission fee for long-term growth rather than a penalty or fine. When you accept volatility as the natural price of building wealth, market fluctuations lose their power to trigger emotional panic.
10. Separate Ego from Net Worth
Many poor financial decisions are made to defend or inflate personal ego. Buying an expensive car on credit, financing a home beyond your budget, or boasting about winning speculative trades are all driven by ego.
True financial resilience requires humility:
- Accepting that you cannot predict short-term economic cycles.
- Being willing to live below your means even when you can afford more.
- Admitting mistakes early and cutting losses quickly.
When you remove ego from financial management, money becomes what it was meant to be: a practical tool for building freedom, security, and choice.
Part 4: Practical Habits for Psychological Financial Peace
Translating psychological insights into daily action requires building simple, sustainable routines that minimize financial stress.
11. Practice the “Cooling-Off” Rule for Major Purchases
Impulse buying is driven by dopamine spikes triggered by novel products. Once the initial excitement wears off, buyer’s remorse sets in.
Establish a mandatory cooling-off period based on purchase size:
- Under $100: 24-hour waiting period.
- $100 to $1,000: 7-day waiting period.
- Over $1,000: 30-day waiting period.
If the desire to purchase the item remains strong after the waiting period, make the purchase intentionally. In most cases, the emotional urge fades, saving you money automatically.
12. Limit Exposure to Financial Noise and Speculative Hype
Modern media channels thrive on generating urgency, fear, and excitement to capture consumer attention. Constant exposure to financial news, stock market updates, and speculative trends creates anxiety and triggers bad trading habits.
Protect your mental peace:
- Focus on macro-level habits (savings rate, diversification, debt reduction).
- Check investment portfolio balances quarterly or semi-annually rather than daily.
- Mute social media channels that promote high-risk trading or flaunt luxury lifestyles.
13. Reframe Spending around “Time Freedom”
The ultimate dividend that money pays is control over your time. Being able to wake up each morning and say, “I can do whatever I want today” is the highest form of personal wealth.
When making spending choices, reframe costs from physical currency into time spent earning it:
$$\text{Real Cost in Working Hours} = \frac{\text{Price of Item}}{\text{Net Hourly Wage}}$$
When you realize that a luxury item costs three full months of working hours, its appeal drops significantly, making saving feel like buying back your future time.
14. Cultivate Financial Alignment with Your Partner
Money is one of the leading causes of relationship stress and divorce. Unspoken financial expectations, different spending habits, and hidden debt create friction between partners.
To build psychological alignment:
- Schedule monthly, non-judgmental “money dates” to review shared goals.
- Maintain complete transparency regarding debt, savings, and individual spending.
- Create a balanced structure with joint accounts for shared expenses alongside individual fun money accounts for personal freedom.
15. Focus on the Process, Not Just the Destination
Obsessing strictly over a specific net worth figure can lead to burnout, frustration, and impatience. Wealth building is a multi-decade marathon, not a sprint.
Learn to find satisfaction in the daily execution of healthy habits:
- Celebrate hitting monthly savings targets.
- Enjoy the peace of mind provided by a fully funded emergency reserve.
- Measure success by your consistency and emotional calm rather than short-term market fluctuations.
Final Thoughts: Mastering Your Mind to Master Your Money
Financial success is not an engineering problem solved by better software or superior intellect. It is a psychological challenge solved by self-awareness, patience, and emotional discipline.
To build lasting wealth starting today:
- Identify your underlying money scripts and emotional spending triggers.
- Automate your savings and investment contributions to eliminate reliance on daily willpower.
- Measure your financial success by the control you gain over your time rather than the status symbols you collect.
By taking control of your mind, you unlock real financial peace and build long-term independence.
Frequently Asked Questions (FAQ)
What is the most common psychological mistake beginners make with money?
The most common mistake is Present Bias combined with Social Comparison—spending money they haven’t yet earned on lifestyle items to project success to others, while delaying saving and investing for their future self.
How can I stop worrying about market volatility when my investments drop?
Focus on your investment horizon. If you are investing for goals 10 to 30 years away, short-term market drops are irrelevant to your final outcome. Reduce how often you check portfolio balances, and remind yourself that market pullbacks are normal features of long-term economic growth.
Is it better to be completely frugal or allow for fun spending?
Extremely rigid frugality often leads to financial burnout and severe spending binges. A sustainable approach includes planned, guilt-free spending on things you genuinely enjoy, balanced by strict discipline in non-essential areas that bring you little value.